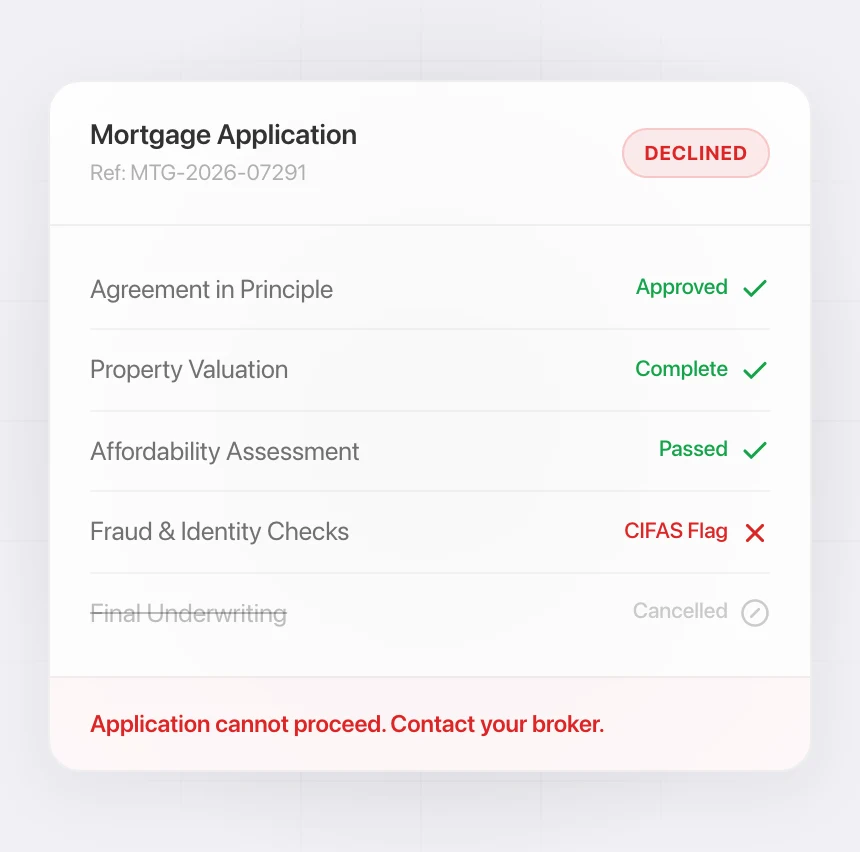
You have a CIFAS marker. You can't bank.
A CIFAS marker doesn't just block credit. It blocks basic banking. Current accounts declined. Savings accounts refused. Payment apps shut down. The rejection letters say "internal criteria" (they never mention CIFAS), but the result is the same: you can't receive your salary, pay your rent, or manage your money like a functioning adult.
The internet is full of outdated forum posts recommending banks that "might" accept you. Half of them have changed their policies. Some have shut down entirely. Others never accepted CIFAS-marked customers in the first place; someone posted a rumour, and it became accepted wisdom.
You need a verified, current answer, not a forum thread from 2022.
What ADVICIFAS Pro Kit actually is
Pro Kit is a subscription service (£3.99/month, cancel anytime) that gives you access to a verified list of banks, EMIs (Electronic Money Institutions), e-money accounts, prepaid cards, and credit unions that may accept customers with active CIFAS markers.
The list is not scraped from forums. It's not a static PDF. It's a live, regularly updated database that's refreshed weekly using a combination of AI research and real-world verification. Every provider on the list has a working website, a live product, and a known CIFAS stance: either they explicitly don't check CIFAS, they assess applications individually, or they're an EMI with different checking processes.
For a detailed look at the types of accounts that remain available, see our guide to bank accounts that accept CIFAS markers.
What you get
Verified banking options
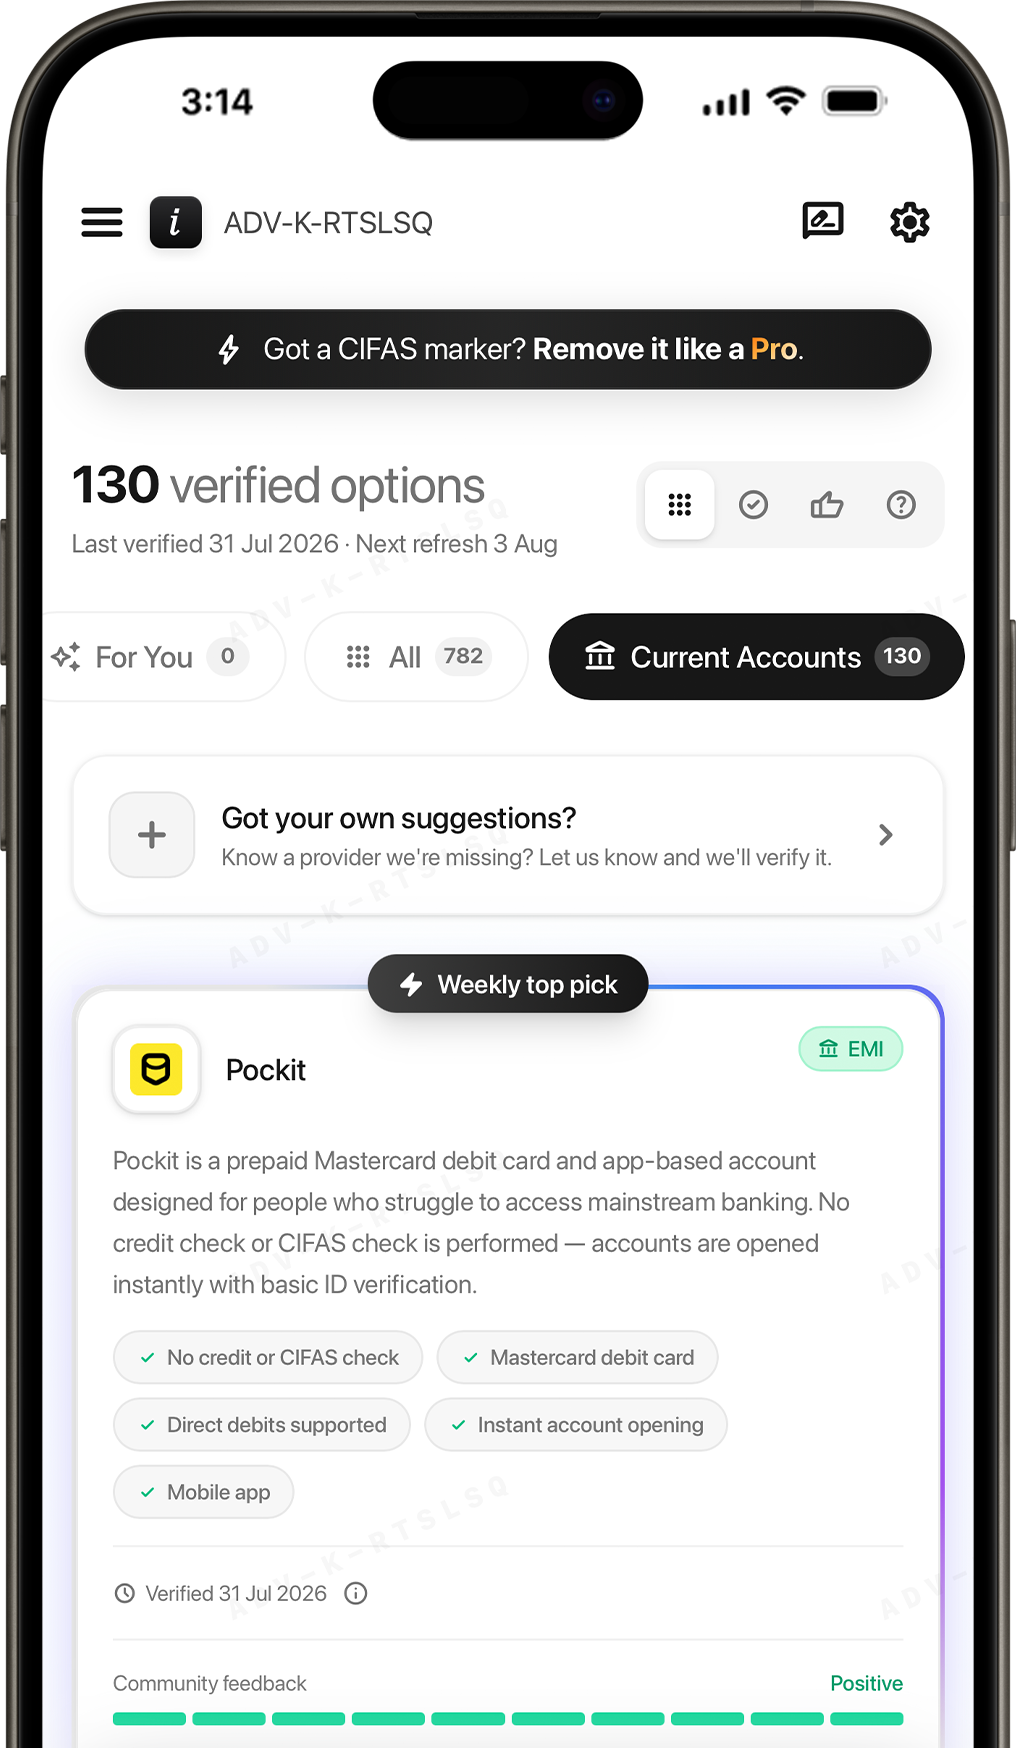
Hundreds of verified financial options across current accounts, savings, phone contracts, car finance, insurance, and money transfers. Each one categorised by type, CIFAS stance, features, and whether they're currently accepting applications. Updated weekly, not annually, not "when we get round to it".
CIFAS stance for every provider
Every provider is tagged with one of three stance labels: "Generally accepts" (generally accepts people with CIFAS markers for the product listed, usually because it isn't a CIFAS member), "Likely to accept" (a strong indication that it accepts people with markers, not yet formally confirmed), or "Case by case" (a CIFAS member that can see your marker, but still accepts some people depending on the marker and their circumstances). You know what you're walking into before you apply.
Personalised recommendations
Tell Pro Kit what you need (personal current account, business account, savings, specific features) and it filters the list to show only the options that match. No scrolling through hundreds of irrelevant providers.
Community feedback
See how other CIFAS-marked users have rated each provider. Real feedback from real people in the same situation, not generic Trustpilot reviews from customers who've never had a CIFAS marker.
Weekly updates
The financial landscape for CIFAS-marked people changes constantly. New EMIs launch. Existing providers change their policies. Products get discontinued. Pro Kit's database is refreshed every week so you're never working with stale information.
Pro Kit helps you find banking options while you have a CIFAS marker. It does not remove the marker; that's what ADVICIFAS Pro does. Many users subscribe to both: Pro to challenge the marker, Pro Kit to bank while the challenge is in progress.
Who Pro Kit is for
Anyone with an active CIFAS marker who needs to access financial services right now. That includes:
- People who've just discovered their marker: your bank closed your account, you can't open a new one, and you need somewhere to receive your salary this month.
- People challenging their marker with ADVICIFAS Pro: the challenge takes time. You need a functioning bank account during the process.
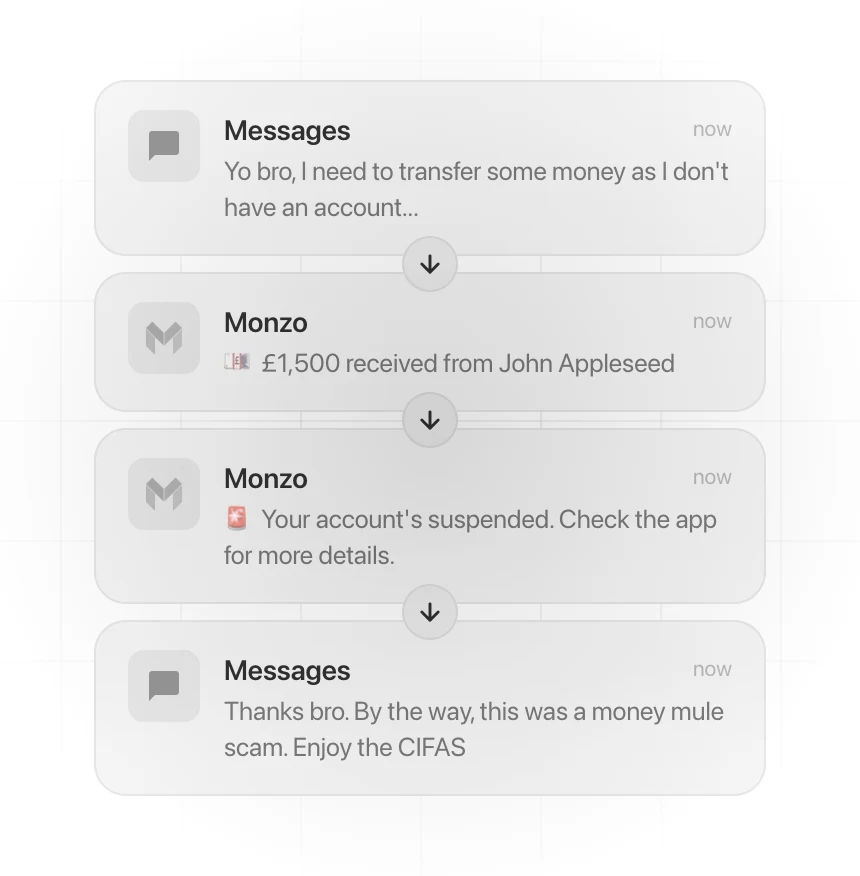
- People who were used as money mules: young people who lost their accounts overnight and have no idea where to turn.
- People whose marker has expired but who are still being declined: some institutions keep internal records even after the CIFAS marker expires. Pro Kit shows you which ones are genuinely open.
- Self-employed people and business owners: a personal CIFAS marker can prevent you opening a business bank account. Pro Kit covers business banking options too.
£3.99/month. That's it.
No contracts. No minimum commitment. No setup fee. Cancel anytime from your account settings: no phone calls, no retention teams, no hoops.
To put that in context: a single declined bank account application costs you time, stress, and potentially a failed reference if a landlord was waiting on your banking details. A single month of not being able to receive your salary costs far more than £3.99. The first provider you successfully open an account with pays for the subscription indefinitely.
Why not just search yourself?
You can. Most people do, at first. Here's what happens:
- Forum posts are outdated. The top results on Google for "bank accounts with CIFAS marker" are 2-4 years old. Providers have changed policies, been acquired, or shut down since they were written.
- Every failed application is a hard search. Some providers run a credit check when you apply. Multiple declined applications in a short period damage your credit score on top of the CIFAS damage.
- You don't know who checks CIFAS. Not every bank checks CIFAS. Not every EMI checks CIFAS. But there's no public list of who does and who doesn't. Pro Kit has this information verified and categorised.
- Policies change without notice. A provider that accepted CIFAS-marked customers six months ago might not today. Pro Kit catches these changes in its weekly refresh cycle.
ADVICIFAS Pro Kit
Bank, Even With
a CIFAS Marker.
Stop getting rejected. We've found the ones that actually say yes. Hundreds of verified financial options that accept CIFAS-marked customers. £3.99/mo, cancel anytime.
Pro Kit vs ADVICIFAS Pro. What's the difference?
They solve different problems:
- ADVICIFAS Pro (£14.99/month): challenges and removes your CIFAS marker. Reads your report, builds legal arguments, drafts complaint letters, analyses institution responses, and escalates through 8 levels. The goal: get the marker deleted. Read the full removal guide.
- ADVICIFAS Pro Kit (£3.99/month): finds you banking options while the marker is active. Verified providers, weekly updates, personalised recommendations. The goal: keep you banking while the marker exists.
Many users subscribe to both. Pro handles the marker removal. Pro Kit handles the banking gap during the removal process. When the marker is removed, you cancel Pro Kit and return to mainstream banking.
Stop guessing. Start banking.
Every day you spend searching forums, applying to random banks, and getting declined is a day wasted. The information exists: which providers accept CIFAS-marked customers, which don't, and which are worth your time. Pro Kit has it, verified and updated.
£3.99/month. First provider you open an account with pays for the subscription for years. Cancel anytime. No contracts.
If you also want to remove the marker entirely, ADVICIFAS Pro handles that, from initial complaint through to Financial Ombudsman referral. For institution-specific strategies, see our institution-specific removal guides.