Banking

Bank Accounts That Accept CIFAS Markers

A practical guide to the bank accounts, e-money accounts, and financial services that still accept customers with active CIFAS markers, and why removing the marker entirely is the better long-term strategy.

A practical guide to the bank accounts, e-money accounts, and financial services available to people with active CIFAS markers.

Share

Why banks reject CIFAS-marked applicants

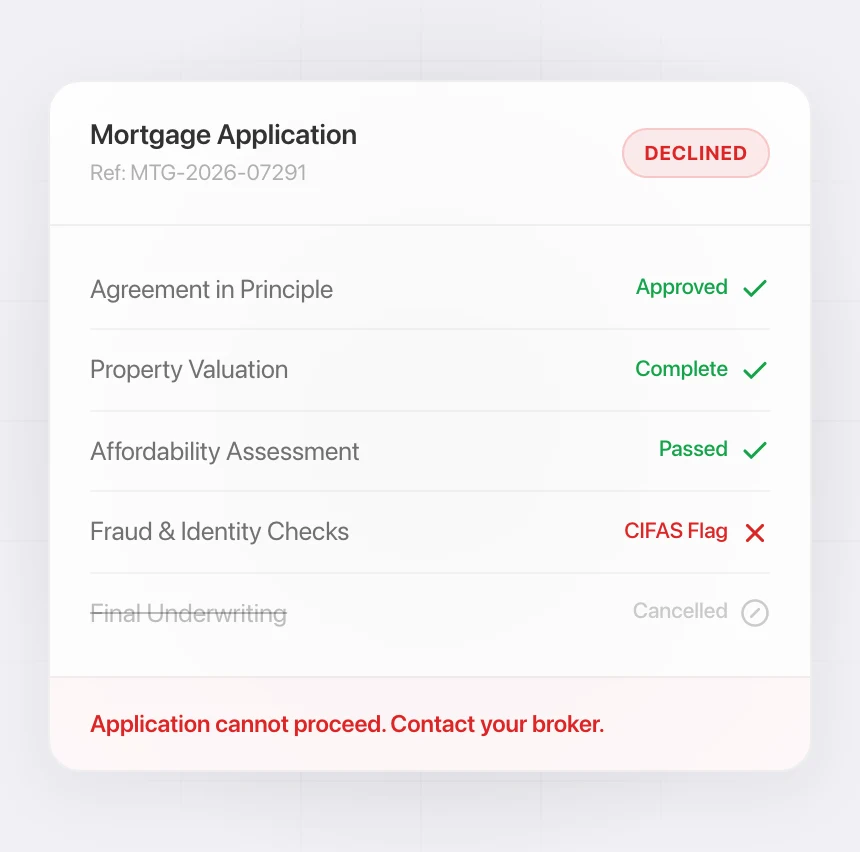
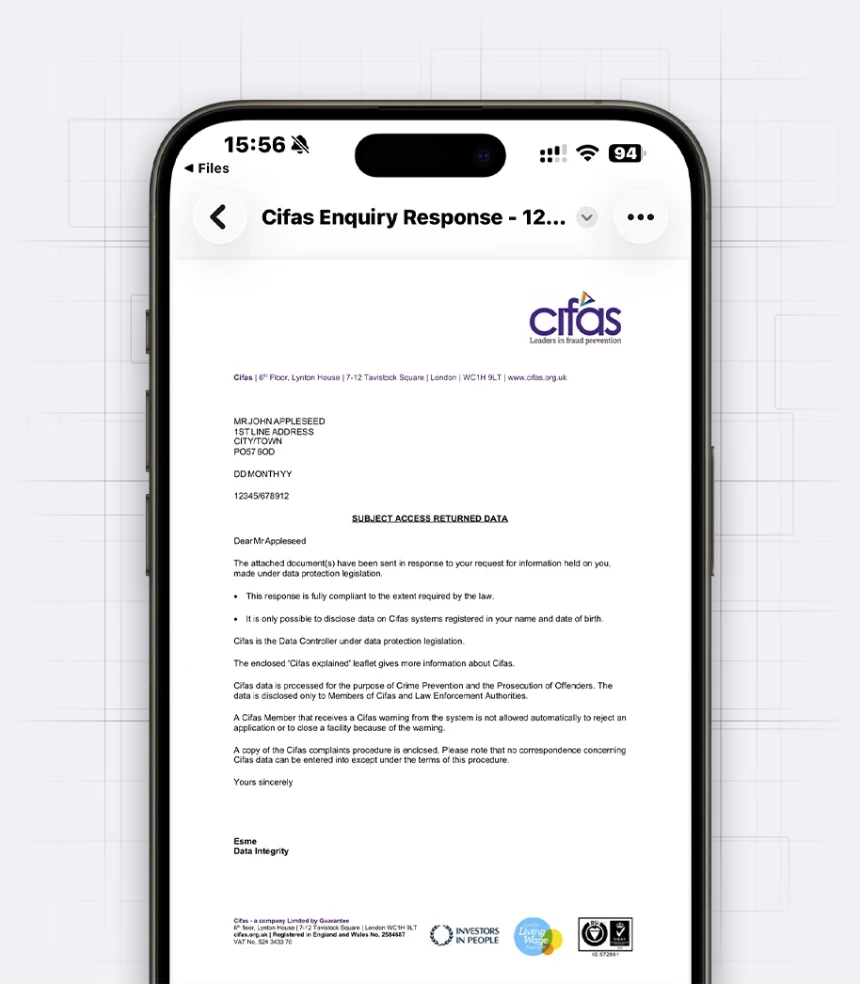
The CIFAS National Fraud Database is shared by over 775 organisations across the UK. When one files a marker against you, every bank, lender, insurer, and employer that checks CIFAS can see it. Apply for a new account and you'll almost certainly be automatically declined; the rejection letter will blame "internal criteria" without ever mentioning CIFAS.

Here's the part most people miss: a CIFAS marker is not a criminal conviction. It's a unilateral allegation by a single institution: no hearing, no notice, no independent verification. Yet it functions as a blacklist across the entire UK financial system for six years.

According to CIFAS Fraudscape 2026, 444,993 markers were filed in 2025 alone, up 6% year-on-year. A significant proportion target people who were victims of fraud, not perpetrators.

If you're not sure what a CIFAS marker is or how the system works, read our complete guide to CIFAS markers.
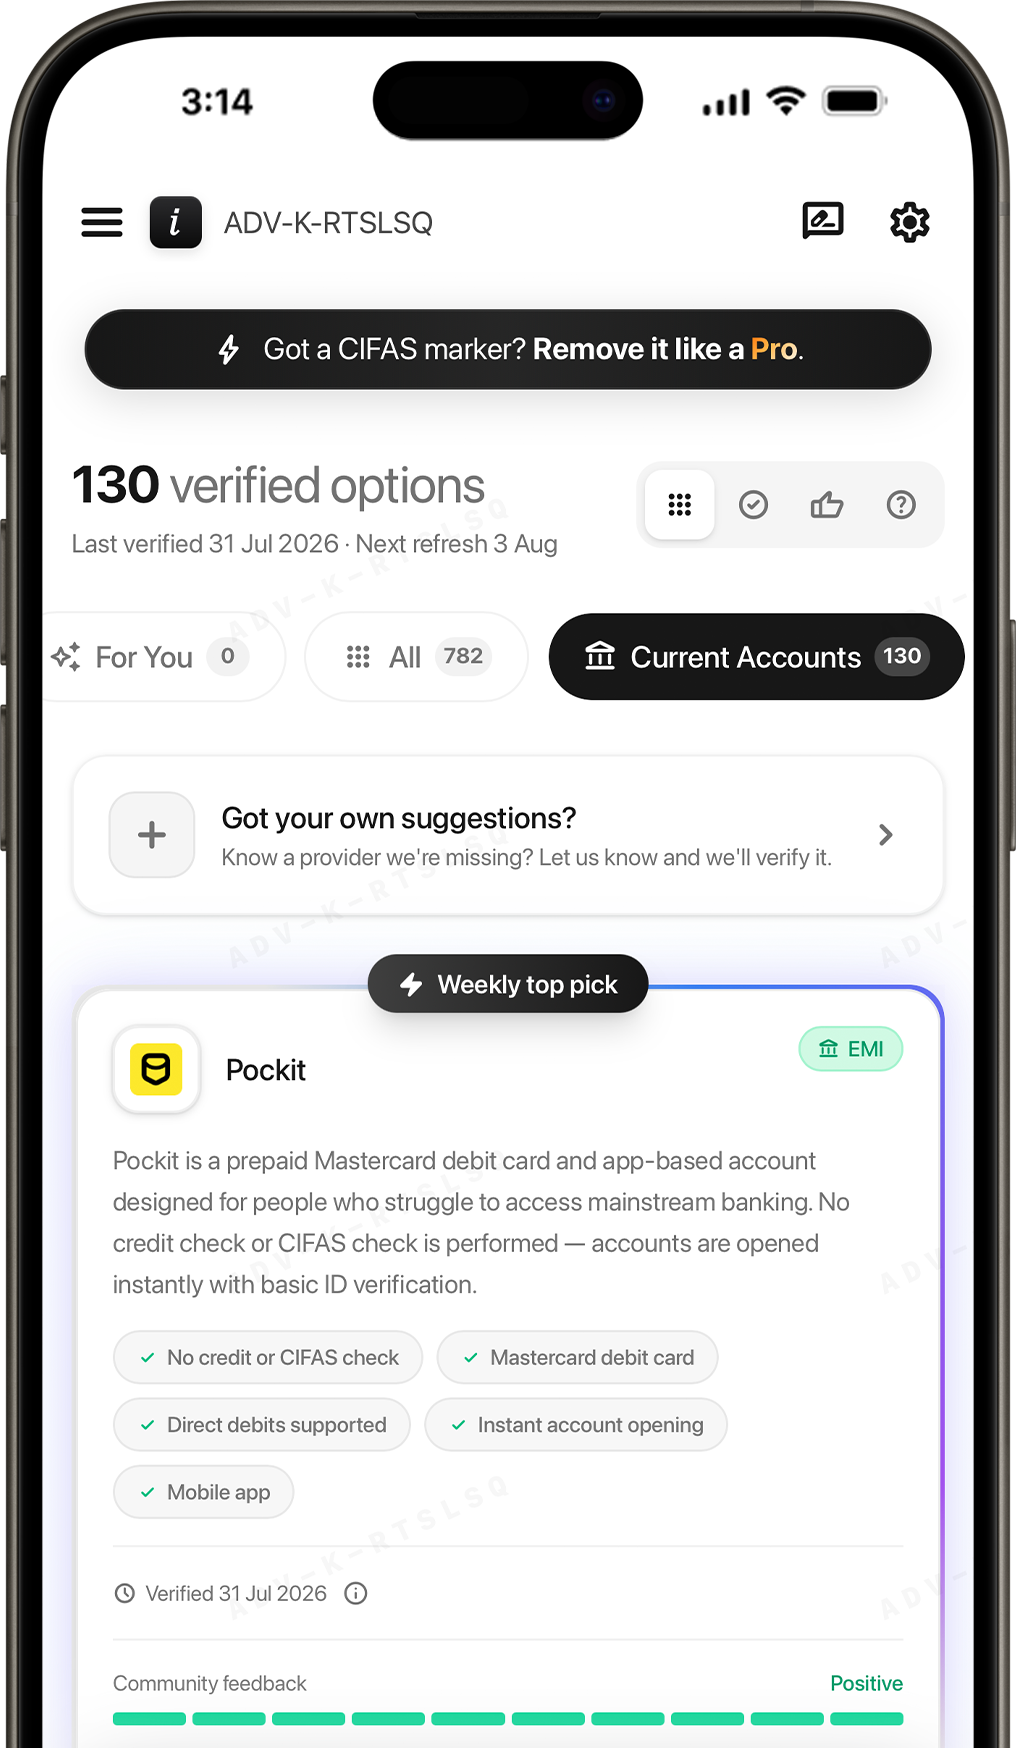
ADVICIFAS Pro Kit

Bank, Even With
a CIFAS Marker.

Stop getting rejected. We've found the ones that actually say yes. Hundreds of verified financial options that accept CIFAS-marked customers. £3.99/mo, cancel anytime.

ADVICIFAS Pro Kit: hundreds of verified financial options for CIFAS-marked people

What types of accounts still accept you

Standard current accounts at high street banks won't work. But four categories of account remain accessible:

Basic bank accounts

The Payment Accounts Regulations 2015 legally require designated banks to offer basic accounts. You get a debit card, direct debits, and cash withdrawals; no overdraft. In practice, some banks still decline when a CIFAS marker is present, citing "money laundering risk". Whether that interpretation holds up legally is debatable, but the result is that even basic accounts aren't guaranteed.

E-money accounts

Electronic Money Institutions (EMIs) aren't full banks but can give you everything you need day to day: sort code, account number, debit card, direct debits, and faster payments. Some check CIFAS; many don't. The trade-off: no FSCS protection; your money is safeguarded but not government-guaranteed up to £120,000.

Prepaid cards

No credit check, no fraud screening; you load money and spend it. Useful as a short-term bridge but limited: fees for loading, no direct debits, and withdrawal charges add up fast.

Credit unions

Some credit unions skip the CIFAS check entirely and assess you on their own criteria. They can offer current accounts, savings, and loans, but availability depends on sharing a "common bond" like living in a specific area.

Personal accounts that accept CIFAS markers

These aren't forum rumours. ADVICIFAS Pro Kit maintains a verified, regularly updated list, confirmed through real testing and member feedback. Here are 2 of them:

Pockit

Prepaid account

Accepts
✓Mastercard debit card
✓Direct debits
✓No credit check
✓Instant account opening
Suits Me

E-money account

Accepts
✓Debit card included
✓Cashback rewards
✓No credit check
✓Instant account opening

These are 2 of the hundreds of verified financial options inside ADVICIFAS Pro Kit. The full list includes detailed comparisons, fee breakdowns, application links, and is updated weekly with new and updated options.

Business accounts that accept CIFAS markers

Your personal CIFAS marker follows you into business banking. If you're a sole trader, director, or partner, most mainstream business banks will decline you, even with a clean business record and strong revenue. Here are 2 that won't:

Countingup

Business current account

Accepts
✓Automated bookkeeping
✓Tax estimates
✓No credit check
✓Sole traders & LTDs
Xace

Business e-money account

Accepts
✓Business debit card
✓Multi-currency
✓No personal credit check
✓API integrations

These are 2 of the hundreds of verified financial options inside ADVICIFAS Pro Kit. The full list covers current accounts, savings, phone contracts, car finance, insurance, and money transfers across 6 categories. See the full list.

What to watch out for

These accounts keep you functional, but they come with trade-offs you need to know about:

payments

Hidden fees. Monthly charges, per-transaction fees, ATM withdrawal costs. A marker-friendly account can cost you hundreds of pounds a year more than a standard current account, a hidden tax on having a CIFAS marker.

credit_card_off

No credit, no overdraft. None of these accounts offer lending. If you need emergency access to funds, the marker blocks you there too.

shield

No FSCS protection. E-money accounts aren't covered by the FSCS. If the provider fails, your money isn't government-guaranteed. For anything over day-to-day spending, that's a real risk.

warning

Watch for "CIFAS-friendly" scams. Some providers in the crypto and fintech space market themselves to CIFAS-marked people with limited regulatory oversight. Always verify the provider is FCA-authorised before handing over money.

Stop managing the damage. Remove the marker.

Everything above is a workaround. You're paying higher fees, accepting worse accounts, and missing FSCS protection, all because of a marker that may not even be justified.

A CIFAS marker lasts six years. During all of them, every bank, mortgage lender, insurer, and employer can see it. The workarounds here address one symptom, bank access, while the marker continues destroying your ability to get a mortgage, insurance, car finance, phone contract, and even a job.

The marker can be challenged and removed at any point. The institution that filed it must hold clear, relevant and rigorous evidence under CIFAS Principle 4, and the Financial Ombudsman Service looks for evidence that you acted with deliberate dishonesty. Many markers are filed on suspicion, automated pattern matching, or against people who were victims. When challenged properly, they get removed.

When it's removed, it's deleted entirely. Not suppressed. Not noted. Gone. You can apply for mainstream accounts, mortgages, and jobs with a clean record, immediately.

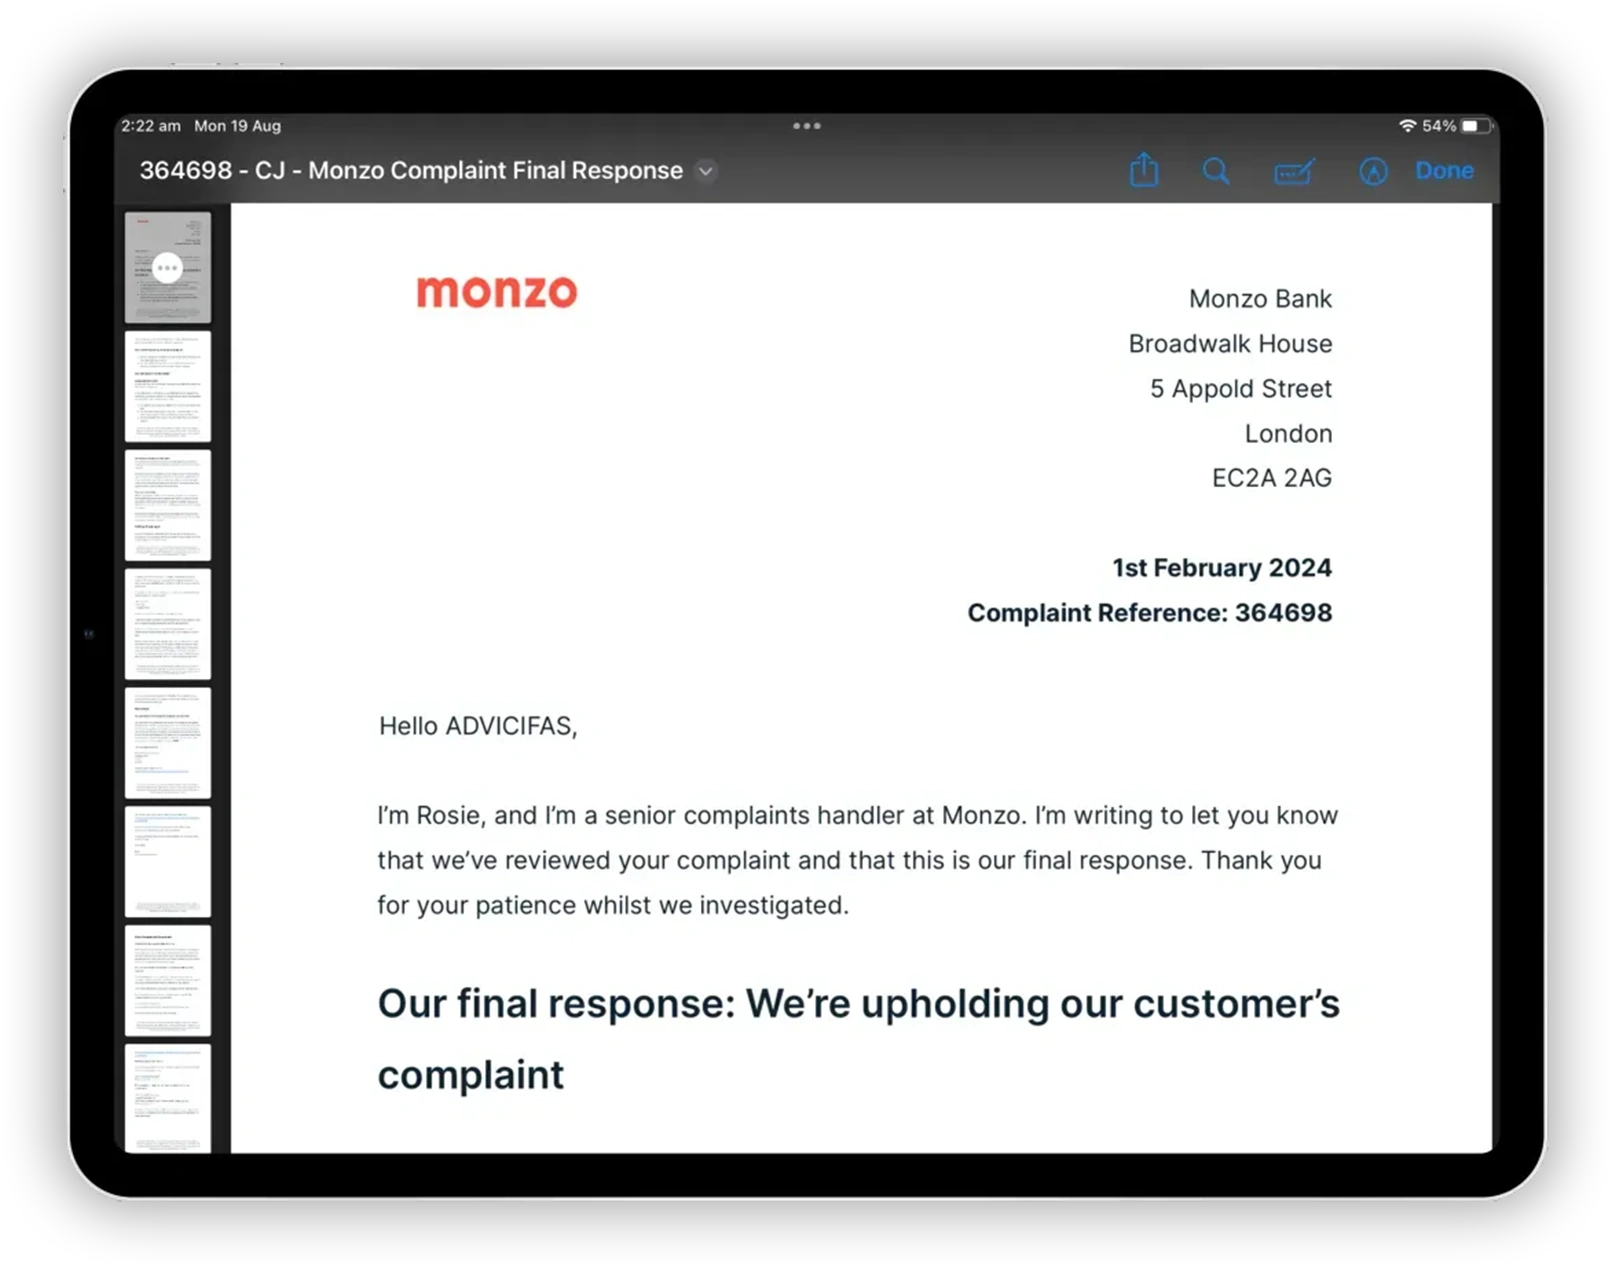
ADVICIFAS Pro manages the entire challenge, from initial complaint through eight escalation levels to the Financial Ombudsman. The system reads your CIFAS report, analyses your institution, builds legally grounded letters citing specific legislation, and guides you through every step. £14.99/month, cancel anytime.

If you need a bank account right now, use the options above, or get the full verified list through Pro Kit. But the marker is the root cause. Removing it permanently is the only way to get your financial life back.

If you know which institution filed your marker, check our institution-specific removal guides for targeted challenge strategies.
Get Started

Unfairly Labelled?
Fight Back.

Upload your CIFAS report and start challenging your marker in under 2 minutes. £14.99/month. Cancel anytime.

ADVICIFAS Pro: CIFAS marker removal confirmed

Frequently Asked Questions

Yes, but your options are significantly reduced. Most high street banks will decline your application. Basic bank accounts, e-money accounts (EMIs), prepaid cards, and some credit unions may accept you. The specific providers that accept CIFAS-marked customers change regularly; ADVICIFAS Pro Kit maintains a verified, regularly updated list.
Most UK banks and financial institutions check the CIFAS National Fraud Database during their application process. However, some e-money institutions, prepaid card providers, and credit unions either do not check CIFAS or apply less restrictive criteria. No major high street bank skips the CIFAS check entirely, but not all providers treat a marker as an automatic decline.
Yes. Several e-money accounts and basic bank accounts that accept CIFAS-marked customers provide a Visa or Mastercard debit card. Some providers offer only virtual cards initially, with a physical card available after verification. Prepaid debit cards are also available without a CIFAS check, though they typically carry higher fees.
Not guaranteed, no. The Payment Accounts Regulations 2015 require designated banks to offer basic accounts, but they can refuse if the applicant poses a money laundering or terrorist financing risk. Some banks interpret a CIFAS fraud marker as meeting this threshold. In practice, some basic account applications are declined despite the legal requirement.
Yes, most e-money accounts provide a UK sort code and account number that can receive faster payments, including salary payments. However, some employer payroll systems flag certain sort codes associated with e-money institutions. If your employer's system rejects the payment, you may need to provide alternative details or ask your employer to add the sort code manually.
E-money accounts are regulated by the FCA and must safeguard customer funds, meaning your money is held separately from the provider's own funds. However, e-money accounts are not covered by the Financial Services Compensation Scheme (FSCS). If the provider fails, your money is in a safeguarded account but is not guaranteed up to £120,000 the way bank deposits are.
A standard CIFAS fraud marker remains on the National Fraud Database for up to six years from the date it was filed. A Protective Registration, which you apply for yourself if you are at risk of identity fraud, lasts two years, and the victim markers (Victim of Impersonation and Victim of Takeover) last 13 months. Markers can be challenged and removed at any point during this period; you do not have to wait for expiry.
In practice, no. Mortgage lenders run CIFAS checks as part of their fraud screening, and a fraud marker will result in an automatic decline from virtually all mainstream and specialist lenders. Removing the marker is the only realistic path to obtaining a mortgage while the marker would otherwise be active.

Was this article helpful?

|

Other Articles

CIFAS Explained1 Sept 2026

Living With A CIFAS Marker

Declined for a bank account. Refused a phone contract. Job offer withdrawn. A CIFAS marker affects your banking, credit, employment, housing, insurance, and mental health. Here's what it's actually like, and how to get it removed.

Read article
Investigation17 Jul 2026

What Happens When You Challenge a Revolut CIFAS Marker

The 65 responses, the unrelated people, the identical sentences. An analysis of how Revolut handles CIFAS marker challenges, based on 22 cases documented between May and July 2026.

Read article
Product25 Jun 2026

ADVICIFAS Pro Kit: Verified Banking Options for CIFAS-Marked People

Pro Kit gives you access to a verified, regularly updated list of banks, EMIs, and e-money accounts that accept customers with CIFAS markers. £3.99/month, cancel anytime.

Read article
CIFAS Explained25 Jun 2026

Can I Get a Mortgage with a CIFAS Marker?

A practical guide to mortgages and CIFAS markers in the UK. Whether you can get approved, which lenders consider applications, what happens to existing mortgages, remortgaging options, and how getting the marker removed changes everything.

Read article
CIFAS Explained25 Jun 2026

CIFAS Markers: What They Are, How to Check, and How to Get Yours Removed

A complete guide to CIFAS markers in the UK. What they are, the 7 types, how long they last, what they affect, how to check if you have one, and the step-by-step process for getting one removed.

Read article
CIFAS Explained24 Jun 2026

I Was Used as a Money Mule; Now I Have a CIFAS Marker

A guide for people who were tricked into money muling and now have a Misuse of Facility CIFAS marker. What happened, why the bank filed it, why being deceived is not fraud, and the step-by-step process for getting it removed.

Read article
CIFAS Explained24 Jun 2026

CIFAS Markers and Employment: Can Employers See Your Marker?

A complete guide to how CIFAS markers affect employment in the UK. Which employers check, which industries, your legal rights, whether you have to disclose, and what to do if a job offer is withdrawn because of a fraud marker.

Read article
Company19 Jun 2026

From Services to Strategy

ADVICIFAS used to remove CIFAS markers for you. Now, ADVICIFAS Pro gives you the system to do it yourself: faster, cheaper, and more effectively.

Read article
CIFAS Explained29 Aug 2025

CIFAS Marker Removal Guide

Everything you need to know about removing a CIFAS marker: who can challenge, how the process works, what legislation applies, and why most people get it wrong.

Read article
Consumer Rights1 Aug 2025

How UK Banks Are Quietly Controlling How You Spend Your Own Money

Your bank can block your payments, freeze your account, and close it without explanation. Here's how it works, why it's happening, and what it means for your financial freedom.

Read article
CIFAS Explained1 Aug 2025

CIFAS Markers Are Not Legal Issues

Why hiring a solicitor to remove your CIFAS marker is almost always a waste of money, and what actually works instead.

Read article