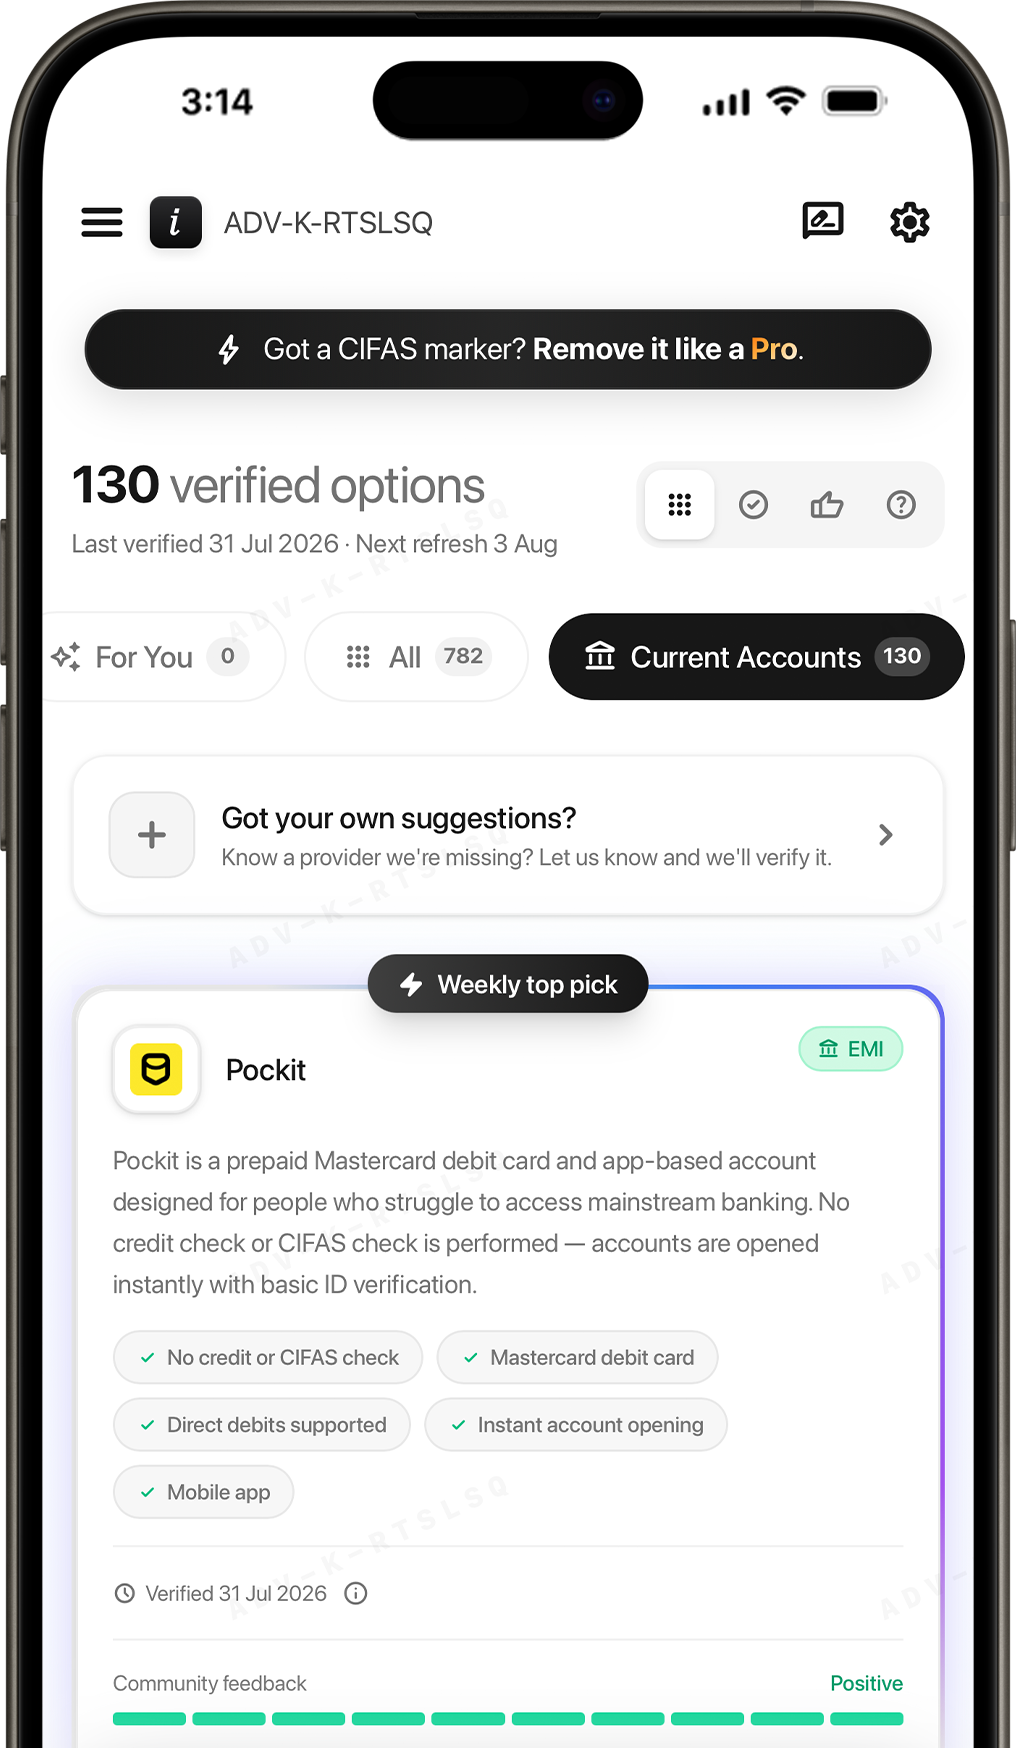
Every card carries a stance label: how open the provider is to people with CIFAS markers for the product listed. It's the quickest way to decide where to apply first.
Generally accepts
Green, with a tick. The provider generally accepts people with CIFAS markers for this product. Usually that's because it isn't a CIFAS member, so it can't screen applicants against the National Fraud Database, where markers are recorded. Some CIFAS members also accept people with markers for particular products, and they carry this label too.
Likely to accept
Blue, with a thumbs up. There is a strong indication that the provider accepts people with CIFAS markers, based on its terms, its privacy policy and feedback from members, but this hasn't been formally confirmed.
Case by case
Amber, with a question mark. The provider is a CIFAS member and can check the National Fraud Database, so it can see your marker. Some people with markers are still accepted, depending on the type of marker and their circumstances.
How the label is decided
When a provider is added, it's checked against the member list CIFAS publishes, by its Companies House company number or, failing that, an exact name match, along with what the provider says about who it accepts. Labels are reviewed regularly and change when the evidence does.
What the label can't tell you
The label is about the provider, not a prediction about you. A provider that's open to people with markers may still turn you down for other reasons, such as:
- your credit history or affordability
- failing its identity or address checks
- where you live, or its own lending and account-opening criteria
Providers can also change their approach, and the member list and registers the labels rely on are kept by other organisations and may not always be up to date.
Always check with the provider before you apply. If you think a label is wrong, tell us at [email protected] and we'll look into it.